If you own a successful trading company, sooner or later someone will tell you that you ought to have a holding company. It might be your accountant, a fellow director, or a person at a networking event who half-remembers something. It’s one of the most common pieces of structural advice given to owner-managed businesses in the UK, and one of the least well explained.
This page covers what inserting a holding company involves, why owners do it, how a share for share exchange works and what it costs. I should say that I’m a solicitor and I don’t give tax advice, so the tax consequences of a holding company, which are significant, are for your accountant or tax adviser. I deal with the legal structure, the documents and the process, and I’ll point out where a tax question arises so that you know to ask it.
What a holding company is
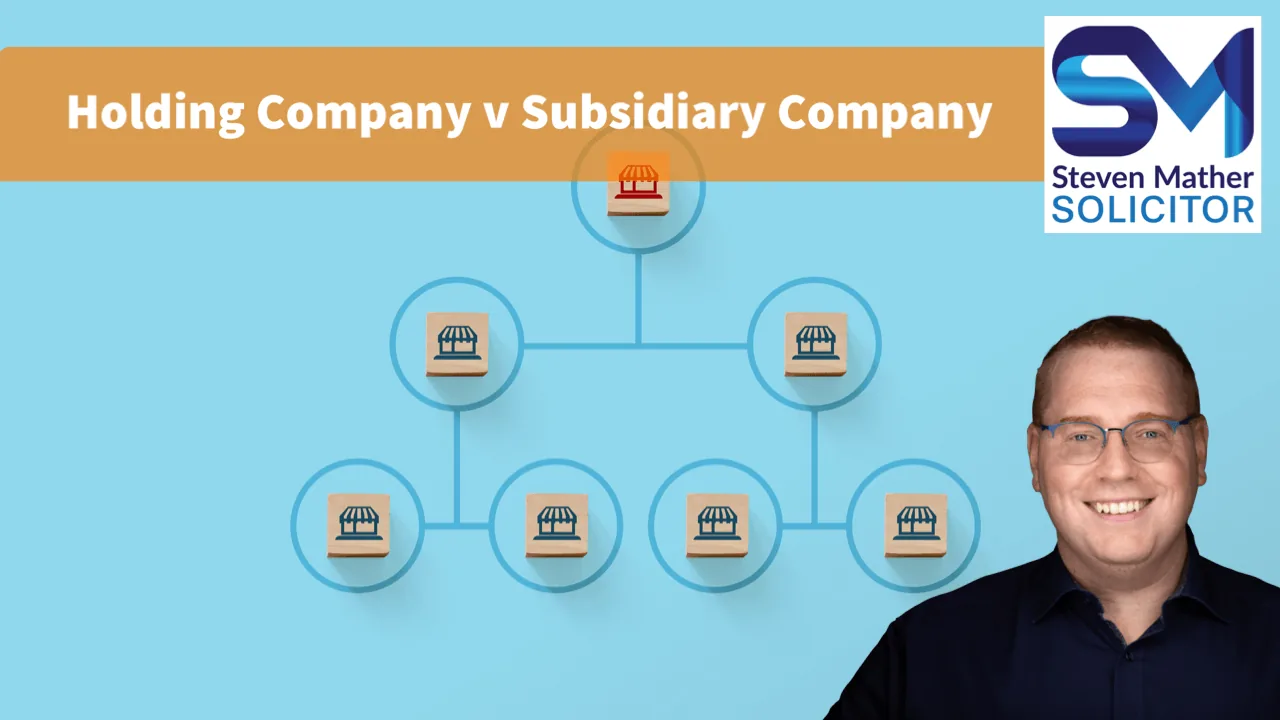
A holding company is a company whose main purpose is to own shares in other companies, as opposed to trading itself. The companies it owns are its subsidiaries, and together they form a group. I’ve written separately about the difference between a holding company and a subsidiary.
Take a trading company, Trading Ltd, which employs the staff, signs the contracts, raises the invoices and carries the commercial risk. Above it you put a new company, Holdco Ltd, which owns 100% of the shares in Trading Ltd. You no longer own Trading Ltd directly; you own Holdco Ltd, and Holdco Ltd owns Trading Ltd.
Nothing changes on the ground, as the same company keeps trading under the same name, with the same contracts, the same staff and the same bank account, and it’s only the layer of ownership above it which changes. A holding company can sit above one trading company or several, and owners with more than one business often use one to bring them together.
Is a holding company right for your business?
Not every business needs one, and doing it because it sounds sophisticated is a poor reason. A reorganisation costs money in legal and tax fees, takes time, and leaves you running two companies where you had one, with two sets of accounts and filings, so those costs need to be justified by a genuine benefit.
It’s more likely to be worth considering where:
- the trading company has built up valuable assets (property, intellectual property, cash) that you’d prefer not to leave exposed to trading risk
- you own, or plan to own, more than one business and want to run them as a group
- you’re planning succession and want flexibility in how ownership passes to family or key people
- a sale is on the horizon and a cleaner structure would make the business easier to sell
- your tax adviser has identified a tax reason that applies to you
It’s less likely to be worth it where the business is small, the assets are modest and there’s no growth, succession or sale plan that the holding company would serve. In some cases the answer is “not yet” or “not for you”, and if that’s the position I’ll say so, as there’s no point in paying for a reorganisation you don’t need.
Why owners insert a holding company
Keeping valuable assets away from trading risk
Every trading business carries risk, whether that’s a contract dispute, an employment claim or a big customer going bust. If the trading company also owns the premises, the intellectual property and several years of retained cash, all of that sits in the company which is exposed to those risks.
A group lets you separate the two, as valuable assets can be held in the holding company, or in a separate subsidiary, so that they aren’t directly in the firing line if the trading company gets into difficulty. This is one of the most useful reasons for having a holding company, and it’s a legal and commercial point as opposed to a tax one. It does have to be done properly, as moving assets has legal and tax consequences of its own and the protection is only as good as the structure and the paperwork behind it.
Growth, acquisitions and new ventures
If you intend to buy other businesses or start new ones, a holding company gives you somewhere to put them. Each one sits in its own subsidiary, with its own risks contained, while you own and control the group one level up. It also tends to make life simpler later on if you want to bring in investment, give key people equity in one business, or sell one and keep the others.
Succession
Because ownership sits at the holding company level, you can bring children, family members or managers into the ownership without disturbing the trading company underneath. How that’s structured for tax, and anything involving trusts or wills, is for your tax and private client advisers. Issuing and transferring the shares is my part, usually along with a shareholders’ agreement so that everyone’s rights are written down. My earlier article on holding companies and estate planning goes into this.
Preparing for a sale
Buyers like clean structures, and a group in which the trading business is separate from the property, the surplus cash and any unrelated ventures lets you sell the trading company and keep the premises, for example. Getting the structure right well ahead of a sale is far easier than trying to untangle it during due diligence, when the buyer’s solicitors are looking at everything, so it’s best dealt with as part of exit planning and well before the sale itself.
Tax
Holding companies are often suggested for tax reasons, such as moving profits around a group. Whether any of that applies to you is a question for your tax adviser and depends on your circumstances and the rules at the time, and I mention it only because it’s often why people ask about holding companies.
How a share for share exchange works
The usual way of inserting a holding company (often called a holdco) is a share for share exchange. A new company is set up, and the shareholders of the trading company transfer their shares in it to the new company. In return, the new company issues shares in itself to those same shareholders, in the same proportions.
Afterwards the holding company owns the trading company, usually all of it, and the original shareholders own the holding company in the same proportions as before, while the trading company carries on as a wholly owned subsidiary.
No cash needs to change hands, as each shareholder ends up with the same slice of the same underlying business, held one step removed. That’s why an exchange is used in preference to a sale for cash, and it’s also why the tax treatment of a properly structured exchange can differ from that of a sale, although whether it does in your case is again for your tax adviser.
The legal steps
Every reorganisation has its own wrinkles, but they generally run in this order.
Planning comes first, which means deciding what sits where, whether it’s only the shares that are moving or property and other assets too, whether there is more than one trading company, and whether there are minority shareholders, option holders or lenders whose consent is needed. This is the stage at which your tax adviser and I need to be talking to each other. They model the tax and confirm that the structure works; I deliver that structure through the documents. Both parts are needed, as a structure which works for tax still has to be implemented correctly in law.
The next step is tax clearance, which your tax adviser leads. The tax treatment of an exchange isn’t automatic, and it’s normal to ask HMRC for advance clearance confirming, broadly, that the exchange is being done for genuine commercial reasons and not as part of a tax avoidance arrangement, and the legal completion shouldn’t run ahead of that.
The holding company is then incorporated with the right share structure, articles and directors. That part is usually done by your accountant or a formation agent, as I don’t form companies, and I’ll specify what’s needed. The share structure isn’t always a copy of the existing company’s, particularly if there are different classes of share or a new shareholders’ agreement is planned.
Next come the transaction documents, which are the core of my work:
- a share exchange agreement, under which the shareholders transfer their shares in the trading company in return for shares in the holding company
- stock transfer forms for the existing shares
- board minutes and shareholder resolutions of both companies, approving the transfers and the allotment of the new shares
- updated statutory registers for both companies
- new share certificates
- anything else the structure needs, for example where assets are moving or where bank security or important contracts have to be dealt with
A change of ownership can also trigger obligations to other people. A lender may have security or covenants which mean its consent is needed, contracts, leases and licences may contain change of control clauses, and a regulated business may need to notify its regulator or get approval. Part of my job is to identify these beforehand so that they can be dealt with properly.
After completion come the Companies House filings, including the allotment of shares and the new persons with significant control position, and the statutory books of both companies are written up. Stamp duty on the share transfers is dealt with at this point, although whether any is payable or a relief applies is for your tax adviser.
Finally, a reorganisation is a good moment to put in place or update a shareholders’ agreement at the holding company level, covering how decisions are made, what happens if a shareholder leaves or dies, and how shares can be transferred. That is much easier to agree while everyone is getting on.
Where a reorganisation goes wrong it is usually in the way it was implemented. There might be resolutions that don’t match the agreement, registers that were never updated, a change of control clause that nobody spotted, or a clearance which was obtained for one structure when the documents deliver a slightly different one. These things tend to come to light years later, often when the business is being sold and the buyer’s solicitor reads the file, and fixing them under pressure costs a good deal more than doing it properly at the time.
Moving property and other assets
A common variation is to move the trading premises out of the trading company and into the holding company, or a separate property company, at the same time or shortly afterwards. If the trading company owns the building and later fails, the building is exposed. If it’s held separately, the property and its rent carry on for the owners whatever happens to the trade, including after the business is sold or you retire.
This is a significant exercise in its own right, as there’s a transfer of title, any existing mortgage and the lender’s consent to deal with, and usually a lease to the trading company. There can also be a real tax cost to moving property, which your tax adviser needs to work out before anyone commits. Where it’s the right thing to do, doing it as part of a planned reorganisation is better than coming back to it later.
What it costs and how long it takes
My fee for inserting a holding company is fixed, at approximately £5,000 to £8,000 plus VAT depending on the number of shareholders and companies and how much else is going on. It’s agreed in writing, with a scope of work, before I start. Moving property, a new shareholders’ agreement and your tax adviser’s fees are separate, and I’ll quote for my part of those at the same time if you want them.
The timetable mostly depends on HMRC, as under section 138 of the Taxation of Chargeable Gains Act 1992, HMRC has 30 days from receiving a clearance application to give its decision, and if it asks for more information the 30 days run again from when that’s supplied. I draft the documents while the application is pending so that they’re ready to sign when clearance arrives. Lender or regulator consent, where it’s needed, can take longer than HMRC.
Common questions
Will it change how the business operates? No, the same company carries on with the same name, contracts, staff and bank account, and only the ownership above it changes.
Do I need HMRC clearance? It isn’t compulsory, but it’s normal to apply for it before going ahead, and your tax adviser makes the application.
Can I move the premises at the same time? Often you can, subject to the tax cost and your lender.
Do you give the tax advice? No, I work alongside your accountant or tax adviser, and if you don’t have one who does this kind of work I can suggest someone.
Next steps
If your accountant has recommended a holding company, or you’re wondering whether you need one, send me the details and let me know who owns the company, what it owns and what you’re trying to achieve. I’ll tell you what the legal side involves and what it will cost. For other kinds of reorganisation, see my restructuring page.